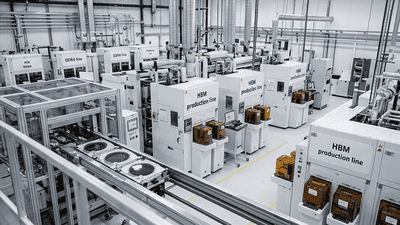
High-Bandwidth Memory (HBM) has evolved from a niche, premium product to a strategic revenue generator for memory manufacturers. Compared with commodity DRAM, HBM commands higher average selling prices (ASPs), deeper integration services, and packaging premiums that lead to significantly superior gross margins. For memory makers facing cyclical commodity DRAM pricing and margin compression, HBM presents a meaningful “P&L repair” lever—a way to improve profitability, stabilize revenue mix, and insulate firms from the worst swings in the DRAM cycle.
HBM versus traditional DRAM: the margin fundamentals
At the simplest level, HBM differs from commodity DRAM along several dimensions that affect unit economics:
- Product complexity: HBM is a stacked memory format requiring advanced die design, TSVs or hybrid bonding, and complex packaging—each step adds value and justifies higher pricing.
- Integration services: Memory makers frequently supply HBM as finished modules (CoWoS, interposer-based packages) rather than bare die, capturing packaging and test margins in addition to wafer revenue.
- Customer willingness to pay: Hyperscalers, OEMs, and accelerator vendors prioritize bandwidth and density over raw $/bit, making them willing to pay premiums for validated HBM performance.
- Smaller, more predictable customer bases: High-end customers often sign long-term contracts with capacity reservations, which improves revenue visibility and reduces spot-market exposure common in commodity DRAM.
These fundamentals combine to create materially higher gross margins for HBM products. Where commodity DRAM margins may swing wildly with supply-demand imbalances and spot-price volatility, HBM’s pricing is more resilient, anchored by system-level value and long-term commitments.
Where the extra margin comes from
Understanding the specific margin drivers helps clarify why HBM is a P&L repair lever rather than just a high-priced product line.
- Packaging and module premiums: Finished HBM modules—especially those requiring advanced interposers, hybrid bonding, or integrated thermal solutions—carry significant ASP premiums above wafer-equivalent pricing. Suppliers that vertically integrate packaging capture this incremental margin rather than ceding it to third-party OSATs.
- Higher ASP per wafer-equivalent: Due to higher complexity, higher per-die capacites, and system-level performance value, the effective ASP for a wafer used in HBM often exceeds that of wafers destined for commodity DRAM.
- Long-term contracts and capacity reservations: Multi-year agreements, prepayments, and capacity reservations reduce revenue volatility and improve predictability of gross margin contribution, enabling better capex planning and utilization smoothing.
- Value-add engineering and co-design services: Memory vendors that provide close-integration services—pinout variants, thermal validation, and joint qualification—can bill for professional services or include the value in pricing, improving blended margins.
- Reduced exposure to spot cycles: HBM demand comes from high-value projects with procurement discipline; therefore, it’s less sensitive to the short-term oversupply dynamics that depress commodity DRAM margins.
Modeling HBM’s contribution to corporate P&L
To quantify HBM’s impact on a memory maker’s profit and loss statement, consider several modeling components:
- Revenue mix: Estimate the proportion of wafer-equivalents shifted from commodity DRAM to HBM die production and the percentage of finished-module sales versus die-only sales.
- ASP differential: Model a premium per wafer-equivalent or per-GB for HBM compared with commodity DRAM. This should reflect both die value and packaging premiums.
- Cost structure: Incorporate higher COGS for HBM—thinner die processes, additional test-time, packaging, TSV/hybrid-bond material costs, and higher yield-learning costs early in ramps.
- Utilization and yield: Early HBM ramps often start with lower yields and higher scrap; model multi-quarter yield improvements. Also account for packaging bottlenecks that can limit finished-unit throughput despite wafer availability.
- Operating leverage: Higher-margin HBM revenues improve gross margin percentage faster than headcount or SG&A increases, creating positive operating leverage over time.
Example illustration: Assume a manufacturer converts 10% of wafer output from commodity DRAM to HBM in year one. If HBM ASPs are 2–3x wafer-equivalent commodity DRAM and packaging captures an additional 20–30% margin, the blended gross margin across the company can rise significantly—even after accounting for higher initial COGS and yield costs. Over two to three years, as yields normalize, HBM’s contribution to company-wide gross margin becomes visible on quarterly P&L statements.
Capital and operational implications
HBM’s margin upside does not come for free. Memory makers must invest in tooling, process development, packaging capacity, and talent to capture these margins sustainably.
- Capex allocation: Building HBM-capable fabs, TSV or hybrid-bond tooling, and in-house packaging lines requires substantial capital. Firms must balance spending between commodity capacity (to maintain cost leadership) and premium HBM lines (to capture margins).
- Packaging capacity: The OSAT and in-house packaging bottleneck is a persistent constraint. Investing in packaging capacity or partnering via capacity reservations is essential to translate wafer output into finished-module revenue.
- Yield ramp teams: HBM ramps require strong yield-engineering teams focused on hybrid bonding, RDL, thinning, and test. Initial yield loss is the primary near-term margin hit and must be actively managed.
- Supply-chain complexity: Suppliers of advanced interposers, underfills, and thermally conductive materials become strategic partners. Memory firms must secure long-term agreements with these suppliers to prevent bottlenecks that cap revenue realization.
Strategically, companies that internalize key packaging steps or secure priority with OSATs capture more of the value chain and therefore more of the margin uplift from HBM. However, this requires careful capital discipline and execution excellence.
Pricing dynamics and customer negotiation leverage
HBM pricing behavior differs from commodity DRAM. Rather than being driven purely by wafer supply and seasonal cycle, HBM prices are co-determined by system-level value and supplier differentiation.
- System-driven value capture: Memory makers can negotiate higher pricing when they demonstrate performance advantages (e.g., validated modules that unlock higher throughput or density for customers).
- Tiered product strategy: Vendors often price HBM tiers (HBM2E, HBM3, HBM3E, HBM4) according to performance and packaging complexity, creating multiple margin pools within the HBM category.
- Contract architecture: Long-term contracts with volume guarantees and price steps tied to yield and volume can stabilize supplier margins while offering customers predictable pricing.
- Spot sales vs. committed supply: While spot HBM sales can be lucrative during supply tightness, sustainable margin improvement depends on capturing recurring contracted revenue rather than opportunistic spot pricing.
Memory makers that position HBM as a system enabler rather than a commodity gain stronger bargaining power in price negotiations and can maintain higher gross margins through structured contracts.
Case studies: how HBM repaired P&Ls in practice
Several public examples illustrate how high-margin DRAM products can materially improve corporate profitability. While exact financials vary and companies rarely break out HBM separately, observable patterns emerge:
- Vertical integration pays: Firms that invested early in packaging and testing (reducing reliance on third-party OSATs) captured larger portions of the ASP premium, translating into faster gross-margin improvement as HBM volumes scaled.
- Anchor customers accelerate margin normalization: Early supply agreements with hyperscalers and accelerator OEMs often include price-premiums and co-investment clauses that offset yield-related costs and support earlier positive margin contributions.
- Effective yield engineering shortens the margin drag: Teams that closed yield gaps faster moved HBM from a margin-consuming strategic investment to a margin-enhancing product line sooner, creating visible P&L improvements within 4–8 quarters of volume ramp.
Memory firms that failed to secure packaging capacity or whose yield ramps lagged saw HBM margins delayed and felt pressure on cash flow as capex spent on capability did not translate rapidly into profitable revenue.
Investor perspective: signals to watch
Investors modeling memory companies should monitor several leading indicators that HBM will materially improve margins:
- Percent of wafer-equivalents converted to HBM-capable processes and reported HBM shipments (if disclosed).
- Capex allocation signaling investment in packaging, hybrid-bond tooling, or in-house assembly lines dedicated to HBM modules.
- Supply agreements, prepayments, or capacity reservations from hyperscalers or OEMs that show contracted future revenue visibility.
- Yield improvement commentary, test-time reductions, and packaging throughput metrics that indicate falling COGS per finished module.
- Gross-margin expansion in quarterly reports tied to product mix improvement rather than cyclical spot-price recovery.
When these signals align—rising HBM mix, falling packaging unit costs, and long-term customer commitments—investors can have greater confidence that HBM is contributing to a durable P&L repair rather than a transient revenue blip.
Risks and countervailing factors
HBM’s margin benefits are compelling, but several risks can limit or delay their impact:
- Packaging and OSAT capacity constraints: If packaging capacity cannot scale with wafer output, wafer-equivalents will stockpile or be sold as lower-margin die, blunting the margin uplift.
- Yield setbacks: Persistent yield problems in hybrid bonding, TSV formation, or fine-pitch RDL can prolong high COGS and negate expected margin improvements.
- Competitive supply responses: When multiple suppliers ramp HBM in parallel, increased finished-module supply could compress premiums, particularly if system-level demand does not keep pace.
- Macro downturns in AI/Cloud capex: HBM demand is tied to AI/HPC growth; a prolonged slowdown in these segments reduces the market for premium modules and weakens pricing power.
- Technological displacement: Future memory innovations (e.g., monolithic 3D DRAM, radical on-die cache changes) could reduce the unique value proposition of HBM over time.
Mitigating these risks involves coordinated investment, conservative yield ramp planning, and securing long-term customer commitments to justify capital outlays.
Strategic moves for memory makers
To maximize HBM’s P&L repair potential, memory manufacturers should consider the following strategic actions:
- Prioritize vertical integration where economically sensible: Bring critical packaging steps in-house or secure long-term, preferential OSAT partnerships to capture packaging margins.
- Focus capex on bottlenecks: Invest in hybrid-bond tooling, RDL capacity, and high-precision test lines to accelerate yield and reduce COGS per finished module.
- Secure anchor customers early: Long-term agreements with hyperscalers and OEMs stabilize demand and justify packaging capex.
- Optimize product mix: Maintain a balanced portfolio that leverages HBM margins to offset commodity DRAM cyclicality while avoiding overexposure to capital-intensive premium segments.
- Communicate transparently with markets: Where possible, disclose HBM mix and margin performance to help investors model margin sustainability more accurately.
Conclusion
HBM represents more than a technological premium; it is a structural profit opportunity for memory manufacturers coping with cyclical commodity pressures. By capturing packaging premiums, securing long-term contracts, and executing disciplined yield ramps, memory makers can use HBM as a P&L repair lever—raising blended gross margins, stabilizing revenue, and improving operating leverage. The degree to which HBM reshapes a company’s financial profile depends on execution: investments in packaging capacity, yield engineering, and customer relationships are prerequisites for turning technical potential into sustained profitability.
For investors, product managers, and corporate strategists, the key is to watch leading indicators—capex allocation, supply agreements, yield curves, and packaging throughput. Where these indicators point to successful scale-up, HBM’s higher gross margins will be a durable and visible contributor to company-level profitability rather than a short-lived premium.